The Mellani Proposal
A Fair Alternative to Double Taxation
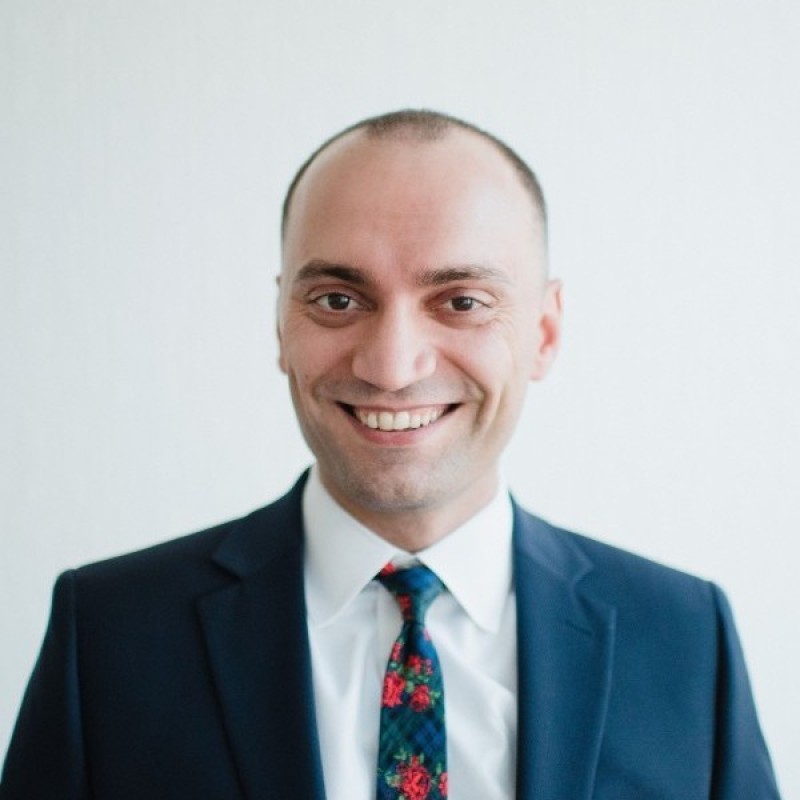
Who is Ervis Mellani?
Ervis Mellani, CFP®, ChFC®, CLU® is a financial planner with over 17 years of experience helping individuals and families navigate complex financial decisions. As a "social worker for people's financial lives," he specializes in bringing awareness and clarity to help clients make educated planning decisions.
Combining domain expertise in financial planning with a passion for technology and intellectual rigor, Ervis has spent the past year developing software tools that respect users' data and privacy while providing sophisticated financial analysis.
Credentials: CERTIFIED FINANCIAL PLANNER™, Chartered Financial Consultant®, Chartered Life Underwriter®
Get in touch: [email protected] · LinkedIn
The Mellani Proposal proposes a fundamental shift in how we think about wealth taxation: instead of layering new taxes on top of existing ones, create a system where taxpayers can voluntarily accelerate their estate tax obligations in exchange for dollar-for-dollar credits. No double taxation. Same revenue for government.
The "Reverse GRAT" Framework
Estate planners are familiar with GRATs - Grantor Retained Annuity Trusts that transfer appreciation out of your estate by paying you an annuity while the remainder passes to heirs. The Mellani Proposal inverts this structure.
Traditional GRAT
You → Assets → Trust → Annuity back to you → Remainder to heirs
Government loses if assets appreciate faster than the hurdle rate
Mellani Proposal (Reverse GRAT)
You → Cash payments → Government → Credits → Applied against estate tax
Government wins by receiving funds earlier (higher NPV)
Why It's Called "Reverse"
Traditional: In a GRAT: You're the annuitant (receiving payments), your heirs are the remainder beneficiaries, government's claim is diminished
Mellani: In the Mellani Proposal: You're the payor (making payments), government is the remainder beneficiary of estate tax, government's claim is settled early
The Economics
Both structures use the same IRS Section 7520 rates for present-value calculations. The difference is direction.
Prepayment calculations use IRS Section 7520 rates, the same methodology used for GRATs, charitable remainder trusts, and other transfer tax valuations.
- GRAT: Freeze asset value, growth escapes estate
- GRAT: Mortality risk on taxpayer (die during term = fail)
- Mellani: Freeze tax obligation, settle early
- Mellani: Mortality risk on government (die early = they got less)
Mortality Risk Allocation
The Mellani Proposal shifts mortality risk TO the government. If you die tomorrow after prepaying, the government got less than the full estate tax would have been. If you live to 100, the government got money 30+ years early.
| Scenario | Traditional GRAT | Mellani Proposal |
|---|---|---|
| Die Early | Assets return to estate (GRAT fails) | Government got paid for obligation that came due immediately |
| Die On Schedule | Transfer succeeds as planned | NPV-neutral for both parties |
| Die Late | More growth escapes estate | Taxpayer gave up capital that could have compounded |
The Core Concept
The Mellani Proposal Principle
Allow taxpayers to make voluntary annual payments toward their eventual estate tax liability. Each dollar paid today earns a dollar credit against estate tax at death. The government gets paid sooner (higher NPV), the taxpayer avoids double taxation.
How It Works
- Taxpayer elects to make voluntary annual payments (e.g., 1-2% of wealth)
- Each payment is credited against their eventual estate tax liability
- At death, estate tax due is reduced by all accumulated credits
- Government receives funds earlier (higher NPV); taxpayer avoids double-dip
Key Benefits
For Government
- Earlier receipt of funds (higher NPV)
- More predictable revenue stream
- Reduced incentive for aggressive planning
- Can be implemented unilaterally (no global coordination)
For Taxpayer
- No double taxation
- Flexibility in payment timing
- Certainty about total tax burden
- Reduced need for complex avoidance strategies
Three Implementation Options
Option 1: Asset Tranche Freeze
Designate a portion of your current net worth as 'frozen' for estate tax purposes. Pay the NPV of projected estate tax on that tranche now. Keep the assets. They (plus all future growth) pass tax-free at death.
- Best for: High-growth assets (startup equity, real estate)
- Risk: If assets decline, you may have overpaid relative to actual liability
Option 2: Liability Percentage Freeze
Prepay a percentage of estimated estate tax liability each year. Credits accumulate and offset final estate tax.
- Best for: Diversified portfolios with stable growth
- Risk: May over or underpay depending on actual wealth at death
Option 3: Credit Account System
Deposit funds into a government-administered account. Funds grow at risk-free rate and are credited against estate tax at death.
- Best for: Maximum flexibility and simplicity
- Risk: Returns may lag wealth growth
Mellani Proposal vs. Zucman Proposal
| Dimension | Zucman 2% | Mellani Proposal |
|---|---|---|
| Double Taxation | Yes (2% + estate tax) | No (credits offset) |
| Total Burden | ~71%+ over lifetime | ~40% (same as estate-only) |
| Government NPV | Higher (more tax collected) | Higher (earlier payment) |
| Taxpayer Choice | Mandatory | Voluntary |
| Administrative Complexity | High (global coordination) | Medium (domestic only) |
| Planning Incentive | Increased (avoid double-dip) | Reduced (no benefit to defer) |
Why This Matters
The Honest Conversation
The debate about taxing billionaires often ignores that estate taxes already capture significant wealth at death. The Mellani Proposal framework brings honesty to this conversation: if we want earlier payment, we can achieve it without cumulative double taxation.
The Zucman Problem
The 2% + estate tax approach maximizes tax revenue but creates:
- Implicit total rates exceeding 75%
- Increased incentives for aggressive planning
- Potential constitutional challenges
- Capital flight to non-participating nations
The Mellani Solution
A credit-based approach achieves policy goals while maintaining fairness:
- Government gets higher NPV from earlier payments
- Taxpayers avoid effective total rates exceeding 75%
- Reduced incentive for avoidance schemes
- Can be implemented unilaterally
Risk Allocation
Key Insight
Under Zucman's proposal, taxpayers bear all the risk: they pay 2% regardless of returns, and still pay estate tax at death even if wealth declines. The Mellani Proposal shares risk more equitably between taxpayer and government.
Scenario Analysis
Bull Market
Zucman: Very high total burden
Mellani: Same as estate-only
Average Returns
Zucman: Moderate extra burden
Mellani: Slight timing advantage for government
Bear Market
Zucman: Confiscatory (tax on declining wealth)
Mellani: Credits may exceed final liability
See the Numbers for Yourself
Our calculator models the Mellani Proposal (Scenario D) alongside Zucman's proposal. Compare the outcomes under your specific assumptions.